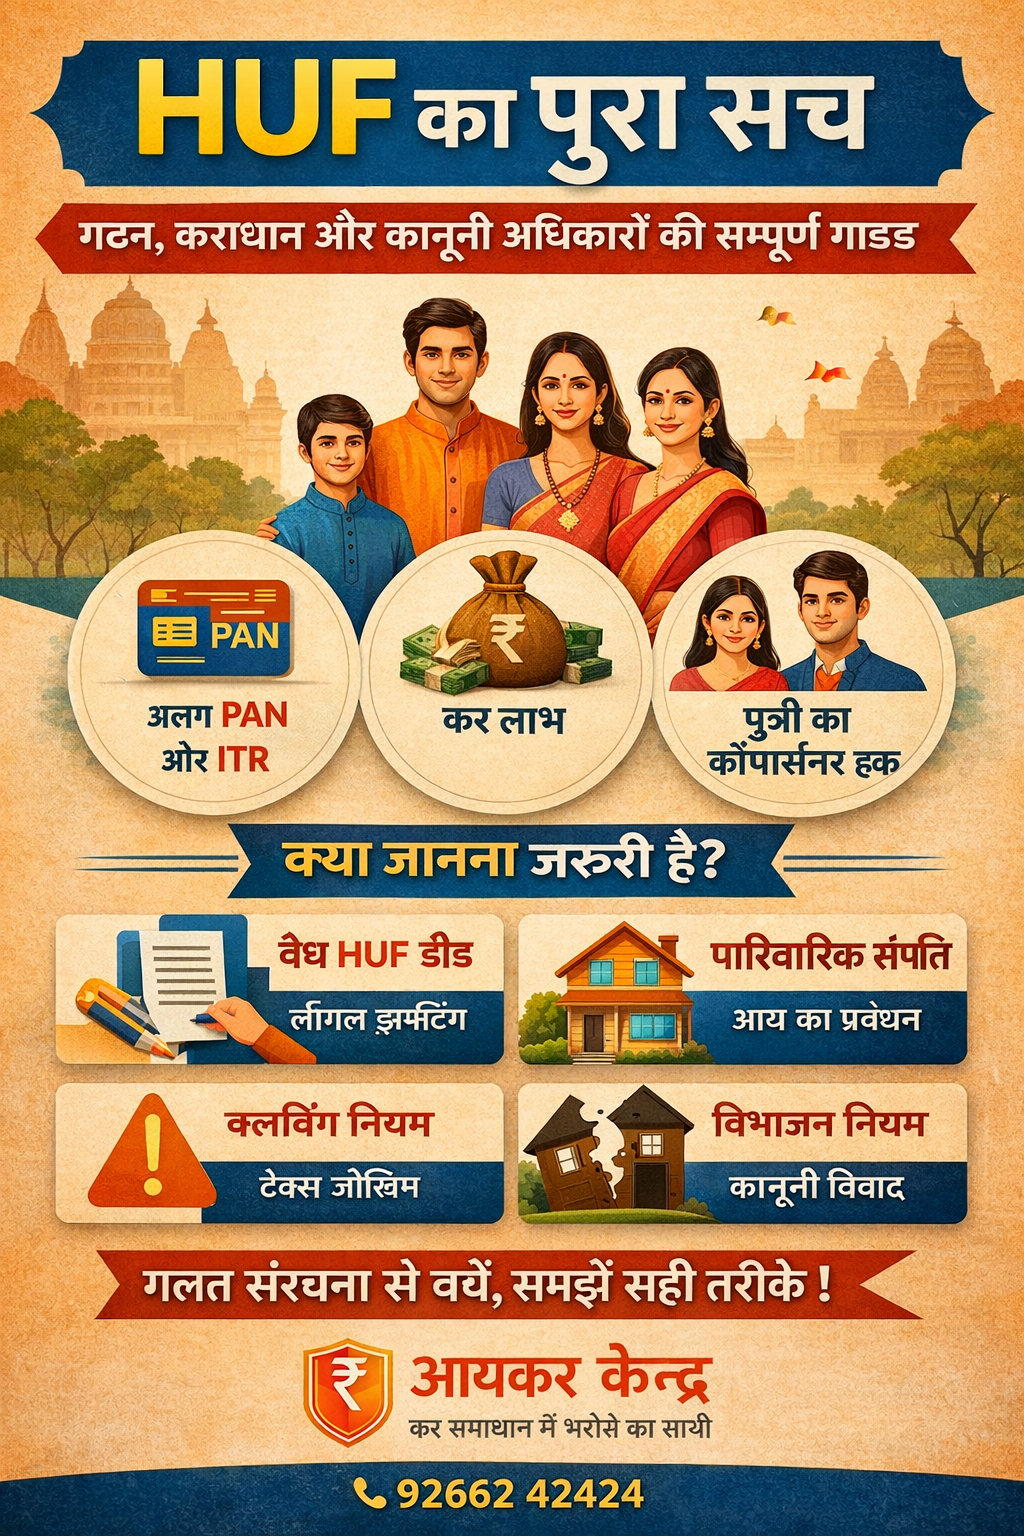

HUF in India: Legal Structure, Coparcenary Rights & Smart Tax Planning Explained
Many families create a Hindu Undivided Family (HUF) only for PAN and bank account purposes.
Very few actually understand:
Who is a real coparcener?
Can a married daughter claim a share?
Can HUF run business?
How does partition work under Income-tax law?
What mistakes invite tax notices?
Let us clarify everything in one comprehensive yet practical guide.
1️⃣ What is an HUF in Law?
An HUF is not created by contract.
It comes into existence by operation of Hindu Law, governed by the Mitakshara School of Hindu Law.
Under the Income-tax Act, 1961, HUF is recognized as a separate “person” under:
Section 2(31) – Definition of Person
This means:
Separate PAN
Separate tax return
Separate basic exemption limit
2️⃣ Who Are Coparceners in 2025?
This is where most confusion exists.
Legal Position (After 2005 Amendment)
Under:
Section 6 of Hindu Succession Act, 1956 (Amended 2005)
A daughter is:
✔ Coparcener by birth
✔ Equal to son
✔ Entitled to demand partition
✔ Liable equally
This was further clarified by the Supreme Court in:
Vineeta Sharma v. Rakesh Sharma (2020) 9 SCC 1
Key principle:
Daughter’s right is by birth, not dependent on whether father was alive in 2005.
Therefore:
| Person | Coparcener? |
|---|---|
| Father | Yes |
| Son (married/unmarried) | Yes |
| Daughter (married/unmarried) | Yes |
| Wife | Member only (not coparcener) |
| Daughter-in-law | Member only |
Marriage does not remove a daughter’s coparcenary rights in her father’s HUF.
This is a major shift from pre-2005 position.
3️⃣ Can HUF Run Business?
Yes.
There is no restriction in Hindu Law or Income-tax Act preventing HUF from:
Carrying on business
Investing in shares, mutual funds
Earning rental income
Trading in securities
Running professional activity (subject to structure)
However:
✔ Business must be in name of HUF
✔ Books of account must be maintained
✔ Income taxed in HUF hands
4️⃣ Sources of HUF Funds – What Is Valid?
HUF funds can arise from:
Initial corpus introduced by Karta
Ancestral property
Gifts from relatives
Income generated from HUF assets
Blending of self-acquired property (with proper declaration)
⚠ Important:
If an individual transfers self-acquired property to HUF without consideration:
Section 64(2) – Income-tax Act
Income may be clubbed back in individual’s hands.
Proper structuring is essential.
5️⃣ Partition – The Most Misunderstood Area
Under Hindu Law:
Coparceners can demand partition.
Under Income-tax Law:
Section 171 – Income-tax Act
AO must recognize partition officially.
Important Rules:
Partial partition after 31.12.1978 is ignored for tax purposes.
Only total partition is recognized.
Distribution on partition is not transfer.
Section 47(i) – No capital gains on distribution at time of partition.
But when recipient later sells asset:
Cost = Original HUF cost
Holding period includes HUF holding
(Section 49(1) + Section 2(42A))
6️⃣ Common Mistakes Families Make
❌ Not including daughters as coparceners
❌ No clear business clause in deed
❌ No proper source declaration
❌ Mixing individual and HUF funds
❌ No books of accounts
❌ No AO recognition of partition
These mistakes lead to:
Tax additions
Clubbing disputes
Family litigation
Bank rejection
7️⃣ Strategic Tax Advantages of Properly Managed HUF
If structured correctly, HUF provides:
✔ Separate basic exemption limit
✔ Separate capital gains exemption
✔ Separate 80C benefits
✔ Asset segregation
✔ Intergenerational planning tool
But remember:
HUF is a tax planning tool, not a tax evasion device.
8️⃣ Governance Principles for Modern HUF Management
In 2025, an HUF should operate like a mini-entity:
Proper deed with business powers
Coparcener consent documentation
Separate accounting
Clear asset registry
Demat and banking clarity
Succession clause for Karta
Dispute resolution mechanism
A casual HUF is a future dispute.
A documented HUF is a wealth vehicle.
9️⃣ One-Line Summary
In 2025, a married daughter stands legally equal to a son in coparcenary rights, and a professionally structured HUF can be a powerful wealth and tax planning structure—if managed with legal clarity and tax discipline.
Relevant Legal References
Section 6, Hindu Succession Act, 1956 (Amended 2005)
Vineeta Sharma v. Rakesh Sharma (2020)
Section 2(31), Income-tax Act, 1961
Section 47(i), Income-tax Act
Section 49(1), Income-tax Act
Section 64(2), Income-tax Act
Section 171, Income-tax Act
📌 Frequently Asked Questions (FAQs) on HUF – Law & Taxation |
1️⃣ What is a Hindu Undivided Family (HUF) under Income-tax Law?
An HUF is a separate taxable entity recognized under Section 2(31) of the Income-tax Act, 1961.
It consists of lineal descendants of a common ancestor and is governed by Hindu Law.
It has:
Separate PAN
Separate Income-tax return
Separate basic exemption limit
2️⃣ Who can be a coparcener in an HUF?
After the Hindu Succession (Amendment) Act, 2005, the following are coparceners by birth:
Father
Son (married or unmarried)
Daughter (married or unmarried)
The legal position was clarified by the Supreme Court in
Vineeta Sharma v. Rakesh Sharma (2020).
Wife is a member but not a coparcener.
3️⃣ Does a married daughter lose her right in her father’s HUF?
No.
Marriage does not affect coparcenary rights.
A married daughter:
Has equal right as son
Can demand partition
Has equal liability
Her right is by birth under Section 6 of the Hindu Succession Act, 1956 (as amended).
4️⃣ Can an HUF carry on business?
Yes.
An HUF can:
Run business
Invest in shares and mutual funds
Earn rental income
Trade in securities
Income is taxable in the hands of HUF, subject to slab rates applicable to individuals.
5️⃣ What are the tax benefits of forming an HUF?
Key advantages:
Separate basic exemption limit
Separate 80C deduction
Separate capital gains exemptions
Income splitting between individual and HUF
However, misuse may attract clubbing provisions under Section 64(2).
6️⃣ Is it mandatory to create a written HUF deed?
Legally, HUF exists by operation of law.
However, practically:
Banks require deed
PAN application requires declaration
Investments require documented authority
Tax scrutiny demands clarity
A properly drafted deed avoids future disputes.
7️⃣ What is the difference between a member and a coparcener?
| Coparcener | Member |
|---|---|
| Has birthright | No birthright |
| Can demand partition | Cannot demand partition |
| Equal share in property | No coparcenary share |
Example: Wife is a member but not a coparcener.
8️⃣ What is partition of HUF under Income-tax Law?
Under Section 171 of the Income-tax Act, only a total partition is recognized for tax purposes.
Partial partition after 31-12-1978 is ignored.
Distribution of assets at partition is not treated as transfer under Section 47(i).
9️⃣ Can self-acquired property be converted into HUF property?
Yes, through “blending”.
However, under Section 64(2), income from such converted property may be clubbed in the hands of the individual who transferred it.
Proper structuring is critical.
🔟 Is HUF better than LLP for tax planning?
It depends on the objective.
HUF → Family wealth structuring + tax efficiency
LLP → Business with limited liability
Individual → Simple salary or professional income
Each structure serves a different purpose.